The Anatomy of Fixed Costs: Deconstructing the Standing Charge
A consumer's standing charge is not a variable administrative fee bolted onto a bill for convenience; it is a fixed-cost recovery mechanism reflecting the physical geography and regulatory economics of Great Britain's electricity and gas transmission and distribution networks. Every property connected to the grid represents a sunk asset base — substations, feeder cables, service lines, meters — that must be maintained, insured, and eventually replaced irrespective of how many kilowatt-hours flow through it. The standing charge is the mechanism by which that fixed asset base is recovered in pence per day, decoupled almost entirely from consumption.
Ofgem's price cap methodology sets this daily levy through a building-block allowance process, not an arbitrary supplier markup. Each supplier's cap is constructed from a stack of cost categories — wholesale energy costs, network charges, policy costs, operating costs, and a permitted margin — and a defined proportion of the non-wholesale elements is apportioned to the fixed (standing charge) component of the cap rather than the variable (unit rate) component. Ofgem reviews this fixed/variable split periodically and has, in recent price cap periods, allowed suppliers latitude to shift small amounts of fixed cost recovery into unit rates or vice versa, subject to headroom rules that prevent the standing charge from ballooning unchecked. The regulatory logic is explicit: costs that do not vary with consumption (network connection charges, environmental obligations levied per meter point, and supplier operating costs tied to simply having a customer on the books) belong in the fixed allowance; costs that scale with throughput (wholesale commodity purchase, balancing mechanism exposure) belong in the unit rate.
This fixed component allocation performs a specific structural function: it ensures that every household connected to the network contributes to the capital and maintenance cost of that connection regardless of whether it draws zero kilowatt-hours or several thousand across a billing period. A vacant property, a holiday let used six weeks a year, and a high-consumption household with electric heating and an EV all draw on the same substation capacity, the same local low-voltage cabling, and the same metering and billing infrastructure merely by being connected. The standing charge is the price of that optionality — the right to draw power on demand — independent of the volume actually drawn.
Network Cost Allocation & Supplier Loss Recovery
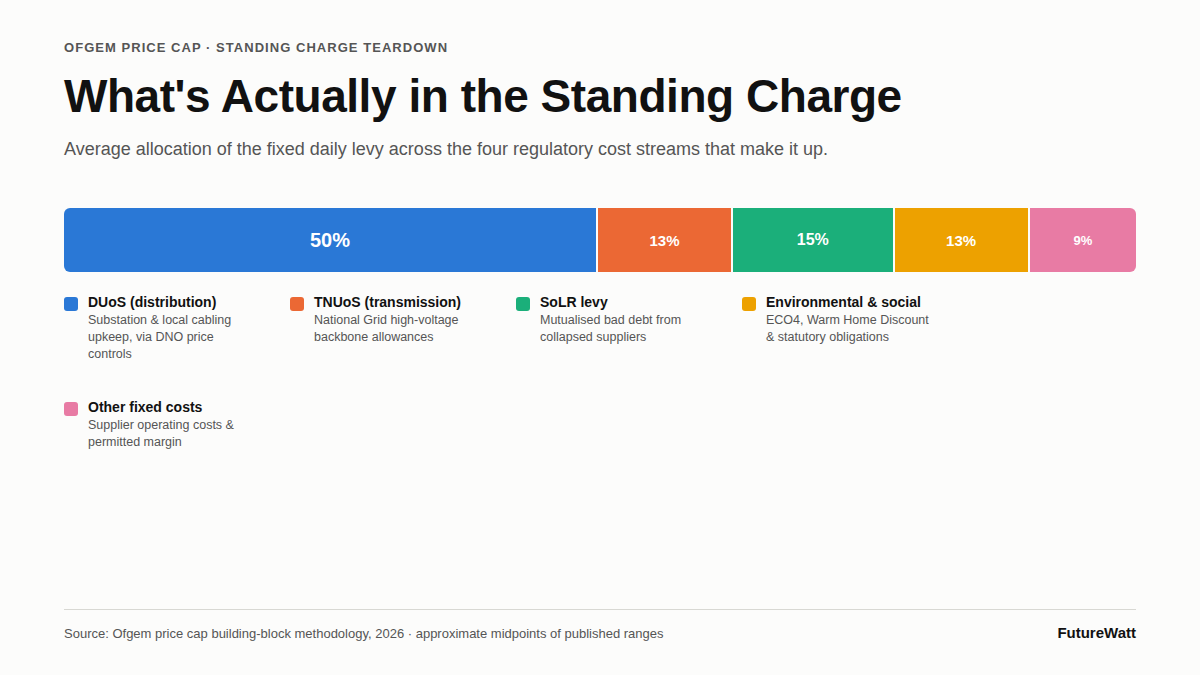
The daily standing charge is not a single line item but a composite of at least four distinct regulatory cost streams, each governed by a different mechanism and each with a different sensitivity to a shift toward volumetric recovery.
Cost Component | Regulatory Mechanism | Average % of Total Daily Charge | Primary Cost Driver | Volumetric Alternative Risk |
|---|---|---|---|---|
Distribution Network Costs (DUoS Fixed Element) | Recovered via DNO price controls (RIIO-2) | ~45%–55% | Substation asset maintenance and local cabling infrastructure | High risk of regressive impact if shifted to volumetric unit rates |
Transmission Network Costs (TNUoS Fixed Element) | National Grid transmission infrastructure allowances | ~10%–15% | High-voltage backbone upkeep and grid balancing connections | Fixed per-node asset charges |
Supplier Failure Levies (SoLR – Supplier of Last Resort) | Regulatory mutualisation mutual fund mechanisms | ~10%–20% | Historical bad debt and customer transition costs from legacy energy company collapses | Fully socialised cross-subsidies |
Environmental & Social Obligation Fixed Apportionment | Statutory green subsidies and vulnerable customer protections (e.g. ECO4, Warm Home Discount) | ~10%–15% | Government-mandated policy targets | Shifting completely to volumetric rates penalises low-income households with high electric heating needs |
Read across the table, the pattern is structural rather than incidental: the two largest components — DUoS and SoLR recovery — are precisely the components regulators are least able to convert to volumetric charging without breaching cost-reflectivity or fairness principles. DUoS fixed costs are asset-driven and geographically fixed; SoLR levies are historical liabilities mutualised across the entire customer base regardless of individual consumption, since the failed suppliers' debts were not incurred proportionally to any current customer's usage.
The Mathematics of Shifting Fixed Costs to Volumetric Rates
The standing-charge-versus-unit-rate debate is frequently framed as a simple fairness question, but the underlying mechanics are a matter of cost-allocation arithmetic with three distinct, quantifiable effects.
- The Regressive Trapping Effect. Moving fixed network maintenance costs out of a flat daily charge and into the volumetric unit rate (p/kWh) redistributes recovery from a per-property basis to a per-kWh basis. Mathematically, a household consuming below the average will see its bill fall, while a household consuming above the average will see its bill rise — but consumption volume correlates poorly with ability to pay. Low-income households in poorly insulated properties requiring high baseline thermal energy, and medically dependent households running oxygen concentrators, dialysis machines, or refrigerated medication around the clock, are structurally high-volume users independent of income. Reallocating fixed cost recovery onto the unit rate therefore imposes the network's fixed cost base disproportionately on exactly the households least equipped to absorb it, converting a flat regressive charge into a consumption-linked regressive charge with a steeper gradient at the high-use tail.
- The Zero-User Gaming Metric. A purely volumetric model creates a free-rider problem at the zero-consumption boundary. Unoccupied second homes, vacant urban developments, and mothballed commercial units remain physically connected to the network — consuming substation capacity, requiring the DNO to maintain live cabling and metering infrastructure to the property — while contributing nothing to fixed cost recovery if that recovery is tied solely to throughput. The standing charge functions as the price signal that closes this gap: it ensures that the mere fact of connection, not the volume drawn across it, generates a baseline contribution to the fixed costs the DNO must recover regardless of occupancy status.
- The Peak Demand Strain. DNOs finance long-term capital expenditure — substation reinforcement, feeder upgrades, capacity headroom for electrification of heat and transport — against a revenue base that RIIO-2 price controls assume will be reasonably stable and predictable. A purely volumetric model ties that revenue base to metered throughput, which fluctuates with weather, behavioural demand response, and the pace of on-site generation and storage uptake. This decouples network revenue from the actual pace of asset deployment and injects volatility into the DNO's investment case, raising the cost of capital for reinforcement projects at precisely the moment the network needs stable, forward-financeable revenue to fund the low-voltage upgrades that electrification of heat and transport demands.
The Smart Tariff Bypass: Mitigating Fixed Levies
Because the standing charge itself is structurally fixed under current price cap methodology, the practical routes available to an engaged consumer operate entirely on the volumetric side of the bill — compressing the unit rate to the point where the fixed charge's proportional weight becomes immaterial, or reducing net import from the grid altogether.
- Exploiting Time-of-Use Arbitrage. Smart tariffs built on half-hourly settlement — Octopus Agile, Tracker, and dynamic wholesale-linked frameworks — expose the underlying wholesale price curve directly to the consumer. Shifting flexible load (EV charging, hot water cylinders, battery charging) into low-price or negative-price windows compresses the blended volumetric rate well below the price-capped average unit rate. Since the standing charge is a flat daily addition, its proportional weight in the total bill falls as the volumetric component is compressed; the fixed charge is not eliminated, but its effective burden per unit of value delivered is neutralised through aggressive off-peak throughput.
- The Microgeneration Co-efficiency Curve. Behind-the-meter solar PV paired with localised battery storage allows a household to self-supply through peak pricing windows, importing from the grid only during low-price troughs or not at all on high-generation days. The standing charge remains flat and unavoidable — it is levied on connection, not import volume — but total system cost falls because the volumetric component it sits alongside shrinks toward zero. The co-efficiency curve describes the point at which additional battery capacity stops materially reducing import volume relative to its capital cost; beyond that point, the standing charge becomes the dominant remaining cost driver and further self-generation investment yields diminishing returns.
- Targeting Structural Tariff Inversions. A small number of tariff products invert the standard cost structure, offering a reduced standing charge paired with a higher per-unit day rate. These products favour genuinely low-consumption households (small flats, part-year occupancy, highly efficient heat pump installations) over high-consumption ones. The crossover threshold is found by equating the two tariffs' total cost functions: for daily standing charges S₁ and S₂ and unit rates R₁ and R₂, the break-even daily consumption k satisfies S₁ + k·R₁ = S₂ + k·R₂, giving k = (S₂ − S₁) / (R₁ − R₂). Below that consumption threshold the low-standing-charge product wins; above it, the standard structure wins — making the calculation, not the headline standing charge figure alone, the correct basis for tariff selection.