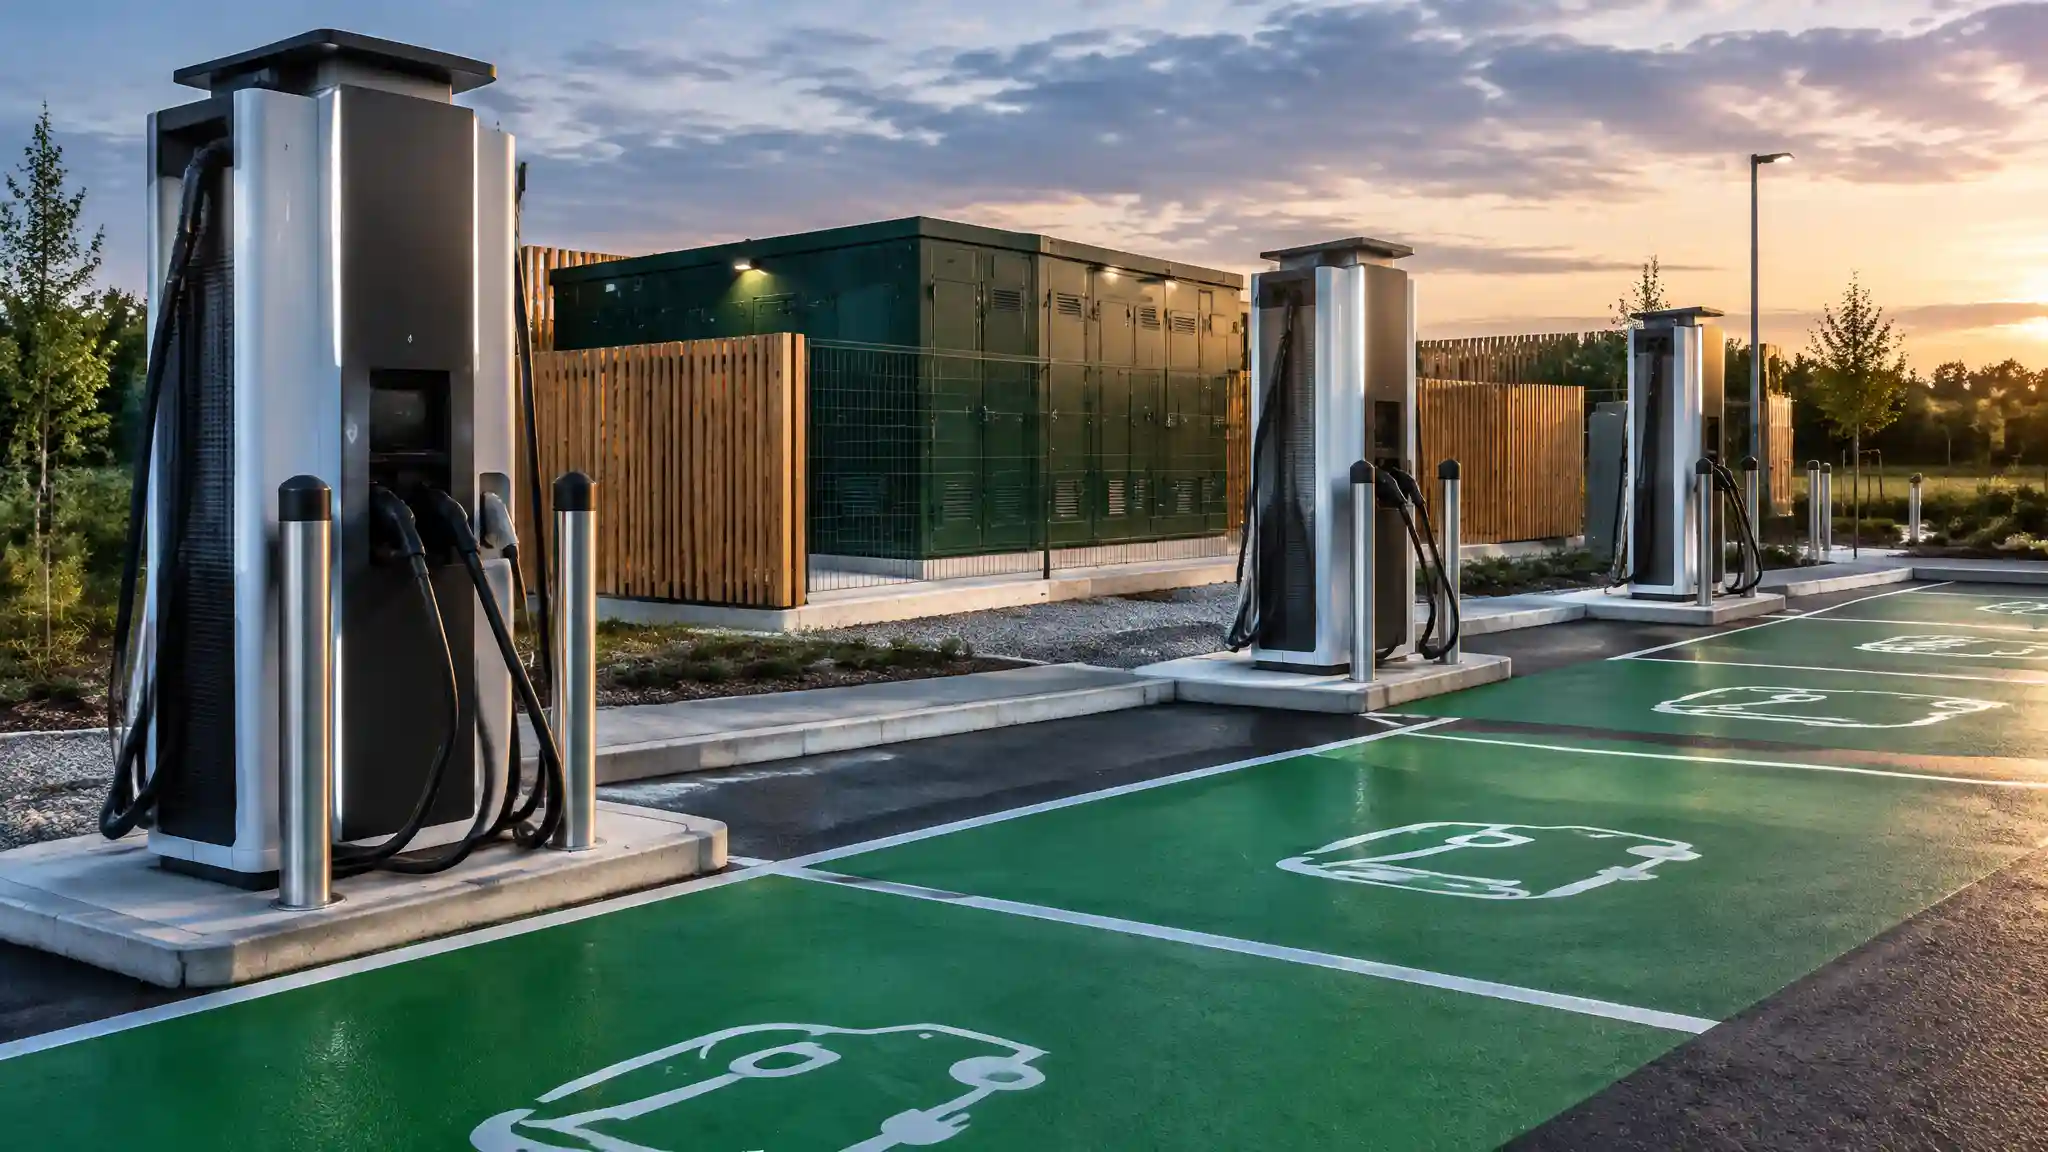
The decisive constraint on any en-route rapid hub is not the charger; it is the grid connection. A 4-stall, 350kW-capable site needs roughly 1MVA of firm capacity, and few roadside plots have it. Securing a dedicated 1MVA substation from the local DNO, including transformer, ring main unit, HV cabling and non-contestable reinforcement fees, can swallow £100,000 to £250,000 before a single charger is unboxed. Connection queues measured in years add holding costs that rarely appear in investor decks.
Hardware is the next capital block. Liquid-cooled 350kW dual-gun dispensers cost around £40,000 to £60,000 each, before power cabinets, back-office software and payment terminals. Heavy-duty civils (HV trenching, reinforced concrete plinths, impact bollards, canopies and bay markings) frequently run to six figures, and accessible bay layouts aligned with PAS 1899, the UK counterpart to US ADA rules, consume extra land per stall. Once these are added together, the £500,000 threshold is crossed comfortably.
Every one of those pounds must be recovered through the tariff over a 10 to 15 year asset life, against utilisation that often starts below 10%. The breakdown below shows where a typical 75p/kWh public rapid charge actually goes.
Cost Component | Share of 75p/kWh | Pence per kWh |
|---|---|---|
Wholesale Power & Distribution Costs | 40.0% | 30.0p |
Grid Connection & Transformer Amortisation | 12.0% | 9.0p |
Hardware CapEx & Maintenance OpEx | 16.0% | 12.0p |
Landlord Ground Rent & Profit Margin | 15.3% | 11.5p |
UK VAT (20% standard rate) | 16.7% | 12.5p |
Total Retail Price | 100% | 75.0p |
The conclusion for developers and fleet operators is blunt: margin is a function of utilisation, not headline price. Sites that negotiate lower capacity charges, share connections with on-site battery storage, or lock in flexible wholesale contracts are the ones that convert a capital-intensive asset into a bankable yield.